
The rule in one sentence
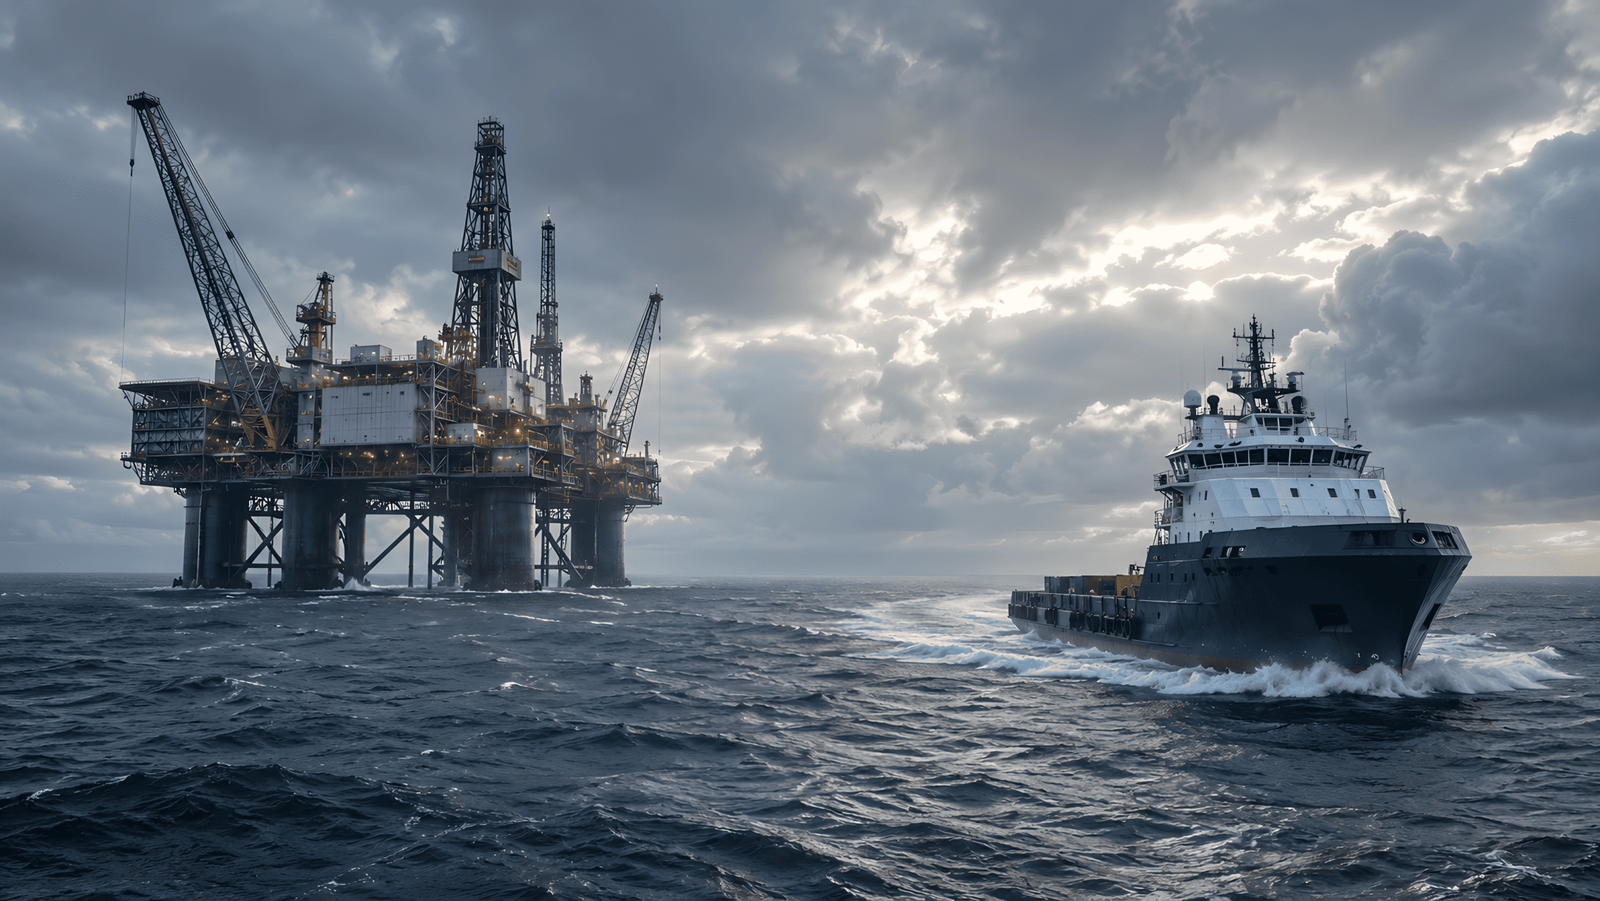
SED is only available to people who work on a ship — and UK tax law is clear that an offshore installation is not a ship. So whether the structure you work on counts as a ship or an installation can decide your entire claim.
Why this catches people out
From where you're standing, an offshore platform and a drilling vessel can feel like the same working world — same sector, same clients, same North Sea. But the tax treatment is completely different. Time spent working on an offshore installation doesn't earn the deduction, even if everything else about your situation would qualify.
For people who move between vessels and installations in a single year, this means only part of their earnings may be eligible.
What tends to count as a ship
There's no simple checklist that settles every case, but broadly, vessels designed to move and operate at sea — carrying cargo or people, or supporting operations while under way — are far more likely to count as ships.
Examples often include:
- Merchant and cargo vessels
- Offshore support and supply vessels
- Many survey and construction vessels
- Drill ships and certain mobile units, depending on how they operate
What tends to count as an installation
Structures that are fixed in place, or that function as a workplace positioned over a field rather than as a vessel navigating the sea, are more likely to be treated as offshore installations.
These commonly include:
- Fixed production platforms
- Certain jack-up and semi-submersible units when operating in installation mode
- Structures engaged in the exploitation of resources on the seabed
The same physical unit can sometimes be treated differently depending on what it is doing at the time — which is exactly why this area needs care rather than assumptions.
The grey area is real
Some units genuinely sit on the borderline, and their status can depend on their function during a particular period. If your vessel isn't clearly a conventional ship, it's worth getting the status confirmed before you rely on it for a claim.
What to do if you're unsure
If you work across different vessel types, keep a record of which vessel you were on for each period of work, not just your dates in and out of the UK. That way, if only some of your earnings qualify, the eligible portion can be worked out accurately rather than estimated.
When a vessel's status is unclear, a specialist review is far cheaper than an HMRC challenge after the fact.